
How to Deal with Nationwide Capital Services (Lawsuits, Settlements, and More)
Relief is the app that helps you save on your debt with smart tools built to do the heavy lifting. With tools like debt reduction requests, you can request lower balances on eligible debts in minutes, and with legal support tools, get help responding to debt notices and review creditor communication for violations. Featured in TechCrunch and backed by leading investors, Relief has already onboarded billions in user's debt. Explore your options and see what's possible.
Who is Nationwide Capital Services?
Nationwide Capital Services collects on past-due consumer accounts placed with it by creditors, or that it has acquired. If you are being contacted by Nationwide Capital Services about a balance, they are not the company you originally borrowed from, which means the Fair Debt Collection Practices Act governs how and when they can contact you. Request written validation of the debt before agreeing to anything, and check your credit report to confirm who currently holds the account.Why Is Nationwide Capital Services Contacting Me?
By the time Nationwide Capital Services gets involved, the debt may have been charged off or sitting in collections for some time. In some cases, you may not even recognize the name because they weren't the company you originally borrowed from.
If you're hearing from Nationwide Capital Services, it's likely because:
- You fell behind on a credit card or loan
- Your original creditor has hired them to collect, or sold them the account
- They believe you owe the full balance
This is the part that matters most: because Nationwide Capital Services is a third party rather than the company you borrowed from, the full Fair Debt Collection Practices Act applies to how they can contact you. Whether or not the debt is valid, you still have rights. And you have time to act before things escalate.
What happens if I Ignore Nationwide Capital Services?
Ignoring Nationwide Capital Services might feel easier in the short term, but it often leads to bigger consequences down the line. When debt collectors don't hear back, they tend to escalate.
If you ignore collection notices or phone calls:
- You may continue to receive repeated letters or calls from their office
- The debt may be reported to the credit bureaus, harming your credit score
- The account may be escalated to a collection law firm, which could result in a lawsuit if it stays unresolved
- If they don't recover, the account may be returned to the creditor and placed with a different agency, starting the contact over
- Fees or interest may continue to accrue where your contract and state law allow it
If you ignore a lawsuit:
- You risk a default judgment, which means the court automatically rules against you
- That judgment can lead to wage garnishment, frozen bank accounts, or even property liens
- In many states, judgments can remain enforceable for years—and they can be renewed. The longer you wait, the fewer options you may have to settle or negotiate.
The better approach is to understand your rights and take proactive steps to resolve it. Relief can help you do all of that—without the guesswork.
Most people sued over a debt never respond — and lose by default. Relief helps you answer in time.
See howWhat are my options with Nationwide Capital Services?
When you're contacted by Nationwide Capital Services, it can feel overwhelming—but you do have a path forward. Here are three ways you can resolve or defend against the debt:
- Make sure the debt is legitimate
- Settle your debt and get a balance reduction
- Protect yourself in lawsuits
Is Nationwide Capital Services a real collector or a scam?
Real agencies and scam callers use a lot of the same language, so verify before you pay anything. A legitimate collector will send written notice, identify themselves as a debt collector, and give you information about the original creditor and the amount owed.
Warning signs worth pausing on: pressure to pay immediately, refusal to send anything in writing, requests for payment by gift card, wire transfer, or a payment app, threats of arrest, or an unwillingness to tell you which company they are and who they're collecting for. If you have doubts, contact the original creditor directly using a number from your own statement rather than one the caller gives you.
A legitimate company can still break the rules—the two questions are separate.
How do I make sure the debt is legitimate?
Before doing anything else, confirm that the debt is accurate. Start by asking:
- Is the debt actually yours?
- Is the amount they claim correct?
- Is the debt still legally collectible (within the statute of limitations)?
- If the account was sold, can they show the chain of ownership back to the original creditor?
Debt collectors don't always have complete or up-to-date records, and accounts that have passed through several hands often arrive with gaps. If you spot anything incorrect, you can dispute the debt.
You have a 30-day window. After Nationwide Capital Services's first written notice, you generally have 30 days to dispute the debt in writing and request validation. Do that and they generally must pause collection until they send verification. Put it in writing—a phone call doesn't create the same record, and it's the written request that triggers the pause.
Be careful with old accounts. In some states a partial payment or a written acknowledgment can restart the statute of limitations, so check where your debt stands before you pay anything toward it.
What could count as a violation?
The Fair Debt Collection Practices Act sets hard limits on third-party collectors, and Nationwide Capital Servicesis one. Most violations happen over the phone, and most go unreported because nobody was writing them down.
Calling before 8 a.m. or after 9 p.m.
Calls must happen during allowed hours—in your local time zone, not theirs. Big agencies run automated dialers across time zones, and mistakes happen. A 6:45 a.m. or 9:15 p.m. call may be worth documenting.
Calling more than 7 times in 7 days
Under CFPB Regulation F, collectors generally can't call more than seven times within seven days about the same debt—and after a conversation, they generally must wait seven days before calling about it again. Nonstop ringing can cross from collection into harassment.
Contacting you after a cease & desist letter
One of the strongest protections you have. After receiving a written cease & desist, Nationwide Capital Services generally must stop—they can confirm receipt or give notice of a specific action, and that's about it. Each additional call, text, or letter may count as a separate violation.
Not identifying themselves as a debt collector
A collector has to disclose that they're a debt collector and that the contact is an attempt to collect a debt. Calls that hide who's calling, or that pose as a survey, a delivery attempt, or an urgent business matter, don't meet that bar.
Skipping the written validation notice
Within five days of first contacting you, a collector generally has to send written notice with the amount owed, the name of the creditor, and how to dispute it. If calls started and nothing ever arrived in writing, that's worth noting.
Calling your workplace after being told not to
Once a collector is told an employer doesn't allow those calls, they must stop calling there. No proof required—telling them is enough.
Discussing the debt with other people
Debt is private. Collectors generally can't discuss it with family, friends, coworkers, neighbors, or employers. They may contact another person once—only to confirm location, never to mention the debt.
Threatening arrest or jail
"You'll be arrested if you don't pay."
Nobody goes to jail for unpaid consumer debt. It's a civil matter, not a criminal one. Arrest threats exist to scare people into paying immediately.
Fake lawsuit or garnishment threats
"Your paycheck will be garnished tomorrow."
Wage garnishment usually requires a lawsuit, a judgment, and a court order—it can't happen instantly. Collectors can't claim legal action was filed when it wasn't, or threaten a suit they don't intend to bring.
Pretending to be attorneys or officials
"This is the legal department."
Collectors can't impersonate law firms, government agencies, police, courts, or credit bureaus—or send fake documents designed to look like court paperwork.
Continuing to collect on a disputed debt
Dispute in writing within 30 days of the first notice and collection generally has to pause until verification arrives. Continuing to press for payment before then, or reporting the debt without noting the dispute, may be a violation.
Inflating the balance
No fake fees, no unauthorized interest, no collecting debt that isn't real or was already paid. When something looks wrong, validation can be requested in writing.
Abusive or threatening language
No swearing, no threats of harm, no humiliation, no intimidation. Behavior designed to degrade or frighten may violate the FDCPA on its own.
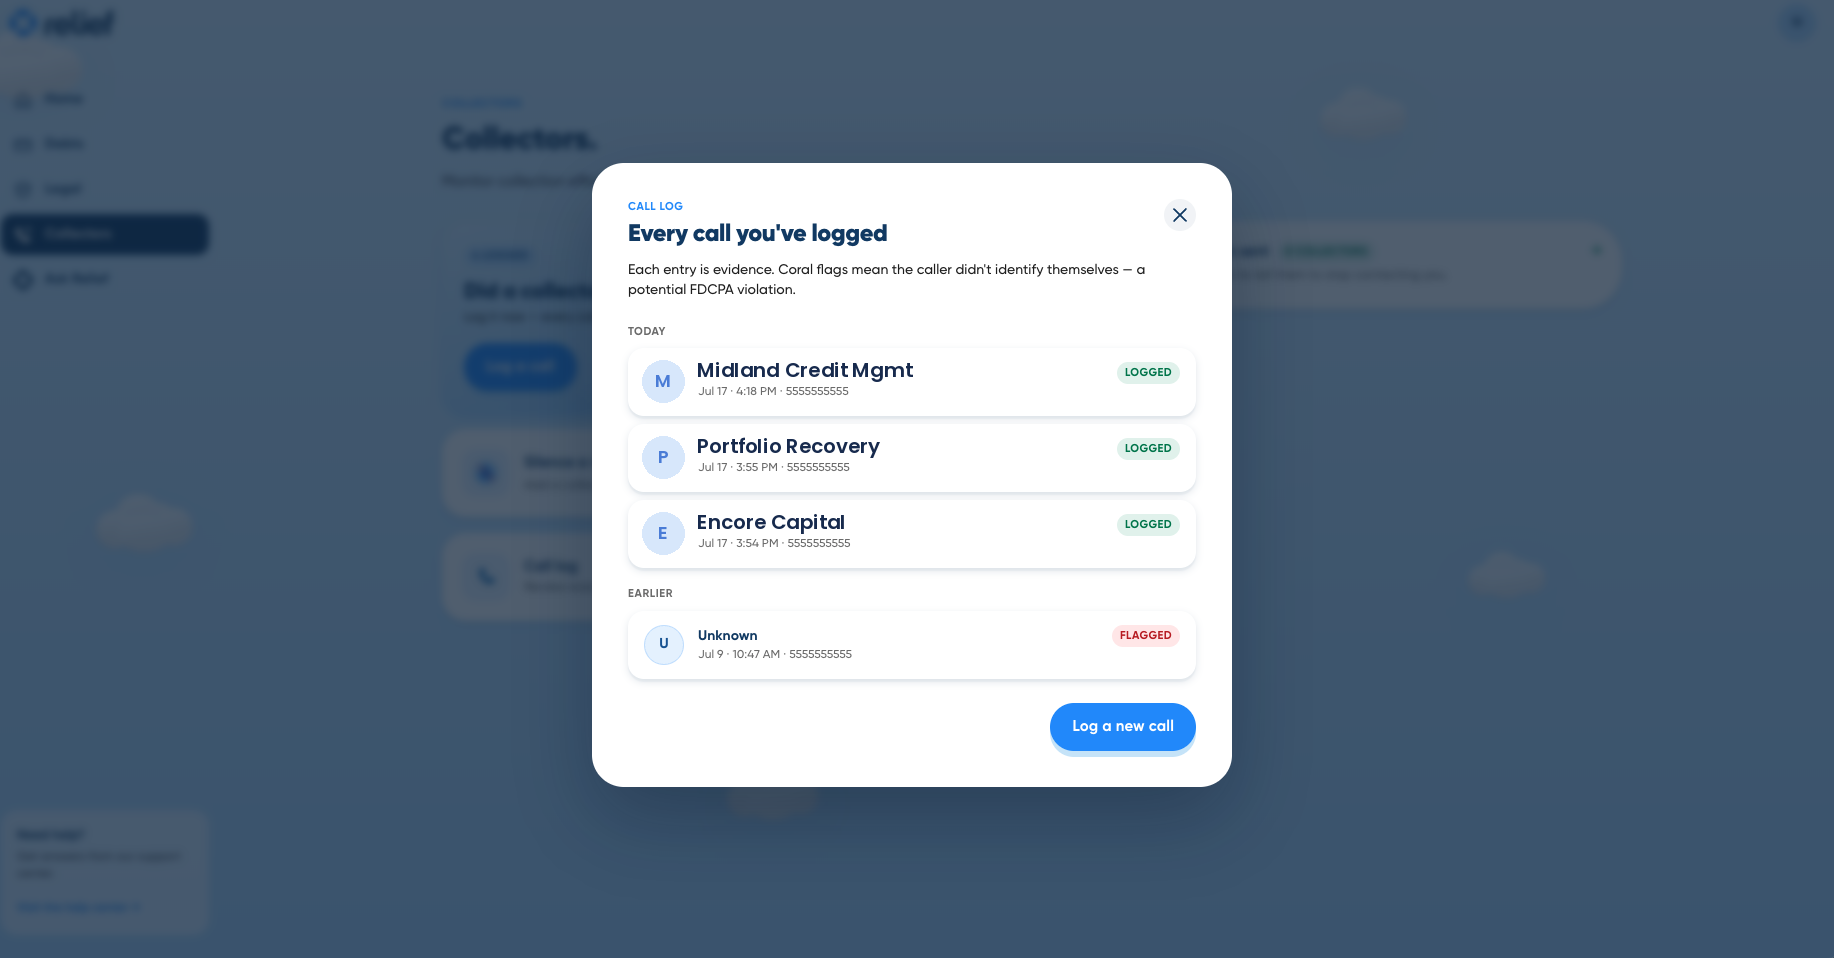
Keep the receipts Relief members log calls, letters, and voicemails in seconds — and the app turns them into a timestamped case file.
See howRelief lets you log every call and letter, flags activity that may deserve a closer look, and keeps it all as a timestamped record. Federal law allows up to $1,000 in statutory damages per lawsuit, and in some cases actual damages and attorney's fees. Outcomes vary, depend on the evidence and the specific conduct, and are never guaranteed.
How do I stop Nationwide Capital Services from calling?
Send a written cease & desist. Once Nationwide Capital Services receives it, they generally must stop contacting you apart from confirming receipt or giving notice of a specific action. Keep proof of delivery—that's what turns any later contact into something documentable.
Worth knowing before you send one: stopping contact doesn't make the debt go away, and it doesn't stop the account from being sold, referred to a law firm, or reported to the credit bureaus. It stops the calls and gives you room to decide what you want to do next.
How do I settle a debt with Nationwide Capital Services?
If the debt is valid and you're in a position to resolve it, you may be able to pay less than the full amount owed. Relief's debt reduction requests are designed to help you take control of the situation—without the endless back-and-forth or pressure tactics of traditional settlement approaches.
With a reduction request, you can:
- Secure a lower payoff amount
- Avoid the stress of phone calls and negotiations
- Submit your request automatically within minutes, right through the Relief app
We've seen users save between 35% and 60% off their original balance, sometimes even more. But it all depends on your creditor and your circumstances. The process is fully automated and self-guided, meaning you stay in control at every step. We work directly with your creditor to present a strong, data-backed offer that increases your chances of approval.
Why does this work?
Because collectors often purchase debt for a fraction of what was originally owed, or are paid a percentage of whatever they recover. Either way, they have flexibility to accept less than the full balance and still come out ahead. A well-structured offer is far more appealing to them than risking a lawsuit that might be dismissed, or waiting on money that may never come.
Ultimately, getting something is better than getting nothing. Settlement offers give both parties a clean resolution: you pay less, and they close the account and move on.
Settling your debt not only saves you money, but also helps close the chapter so you can start rebuilding your credit and move forward without the constant stress of collections.
Get the terms in writing before you pay. Confirm the amount, that the balance is treated as resolved, and how the account will be reported to the credit bureaus afterward. Forgiven debt over a certain amount may also be reported to the IRS as income, so it's worth asking about.
What if Nationwide Capital Services isn't eligible for automated requests?
Eligibility varies, and not every creditor supports requests submitted through the app. If Nationwide Capital Services isn't currently eligible, Relief can still help you prepare:
- Estimated benchmark data, where available
- A conversation blueprint with suggested talking points
- Guidance on what to gather before you reach out
- Recommended questions to ask
You stay in control and decide whether to contact Nationwide Capital Services directly.
Relief makes it easy to request a lower balance. Your creditor decides from there.
Get ReliefWill Nationwide Capital Services settle for less?
Collectors will often settle for less than the full balance you owe. Many people are able to resolve their accounts for less, especially if the debt is older or you're able to make a lump-sum payment. That said, is under no obligation to make an offer and the outcome depends specifically on your account.
Can Nationwide Capital Services sue me?
Generally yes—though not always under this name. Agencies that collect on behalf of someone else usually refer accounts to a collection law firm rather than filing suit themselves, while agencies that purchased the account outright can sue in their own name. So a lawsuit over this debt might list Nationwide Capital Services, a law firm acting on their behalf, or the company that now owns the account. If court papers arrive, check the plaintiff against every name that has contacted you about this debt—an unfamiliar name on a summons doesn't mean it isn't yours.
Either way, ignoring it is the worst outcome. Once you're officially served with court documents—a summons and complaint—you're on the clock. Most courts give you just 14–30 days to respond, depending on your state.
Missing the deadline is how default judgments happen
If you ignore the summons, the judge may issue a default judgment, giving the plaintiff the legal right to garnish your wages, freeze your bank accounts, and add court fees and legal costs to your debt.
Filing a response is critical. It keeps the case alive, makes the other side prove what they're claiming, and usually leaves the door open to settle.
A summons notifies you of the lawsuit and includes key details like:
- The name and location of the court
- The names of both parties
- Your case number
- Deadlines for your response
A complaint outlines what the creditor is claiming, often in numbered paragraphs. Together, these documents kick off the legal process, and the clock starts ticking.
Note that disputing the debt and answering a lawsuit are two different deadlines. The 30-day validation window doesn't pause the court's clock.
And with Relief's legal support tools, you don't have to do it on your own.
Here's how Relief helps you respond:
- AI-assisted review of the summons, complaint, and any notices you've received
- Response drafting support and instructions for filing your answer
- A review of the account and the contact history for potential violations
- Access to independent attorneys at preferred pricing, with a free consultation scheduled in the app
This not only protects you from default judgment, but also gives you the option to still settle the debt—often for less than the full amount.
How to Get Help
Whether you're trying to slow the calls down, resolve the balance, or respond to a notice, your Relief membership includes tools for each of those—without the stress, guesswork, or endless phone calls.
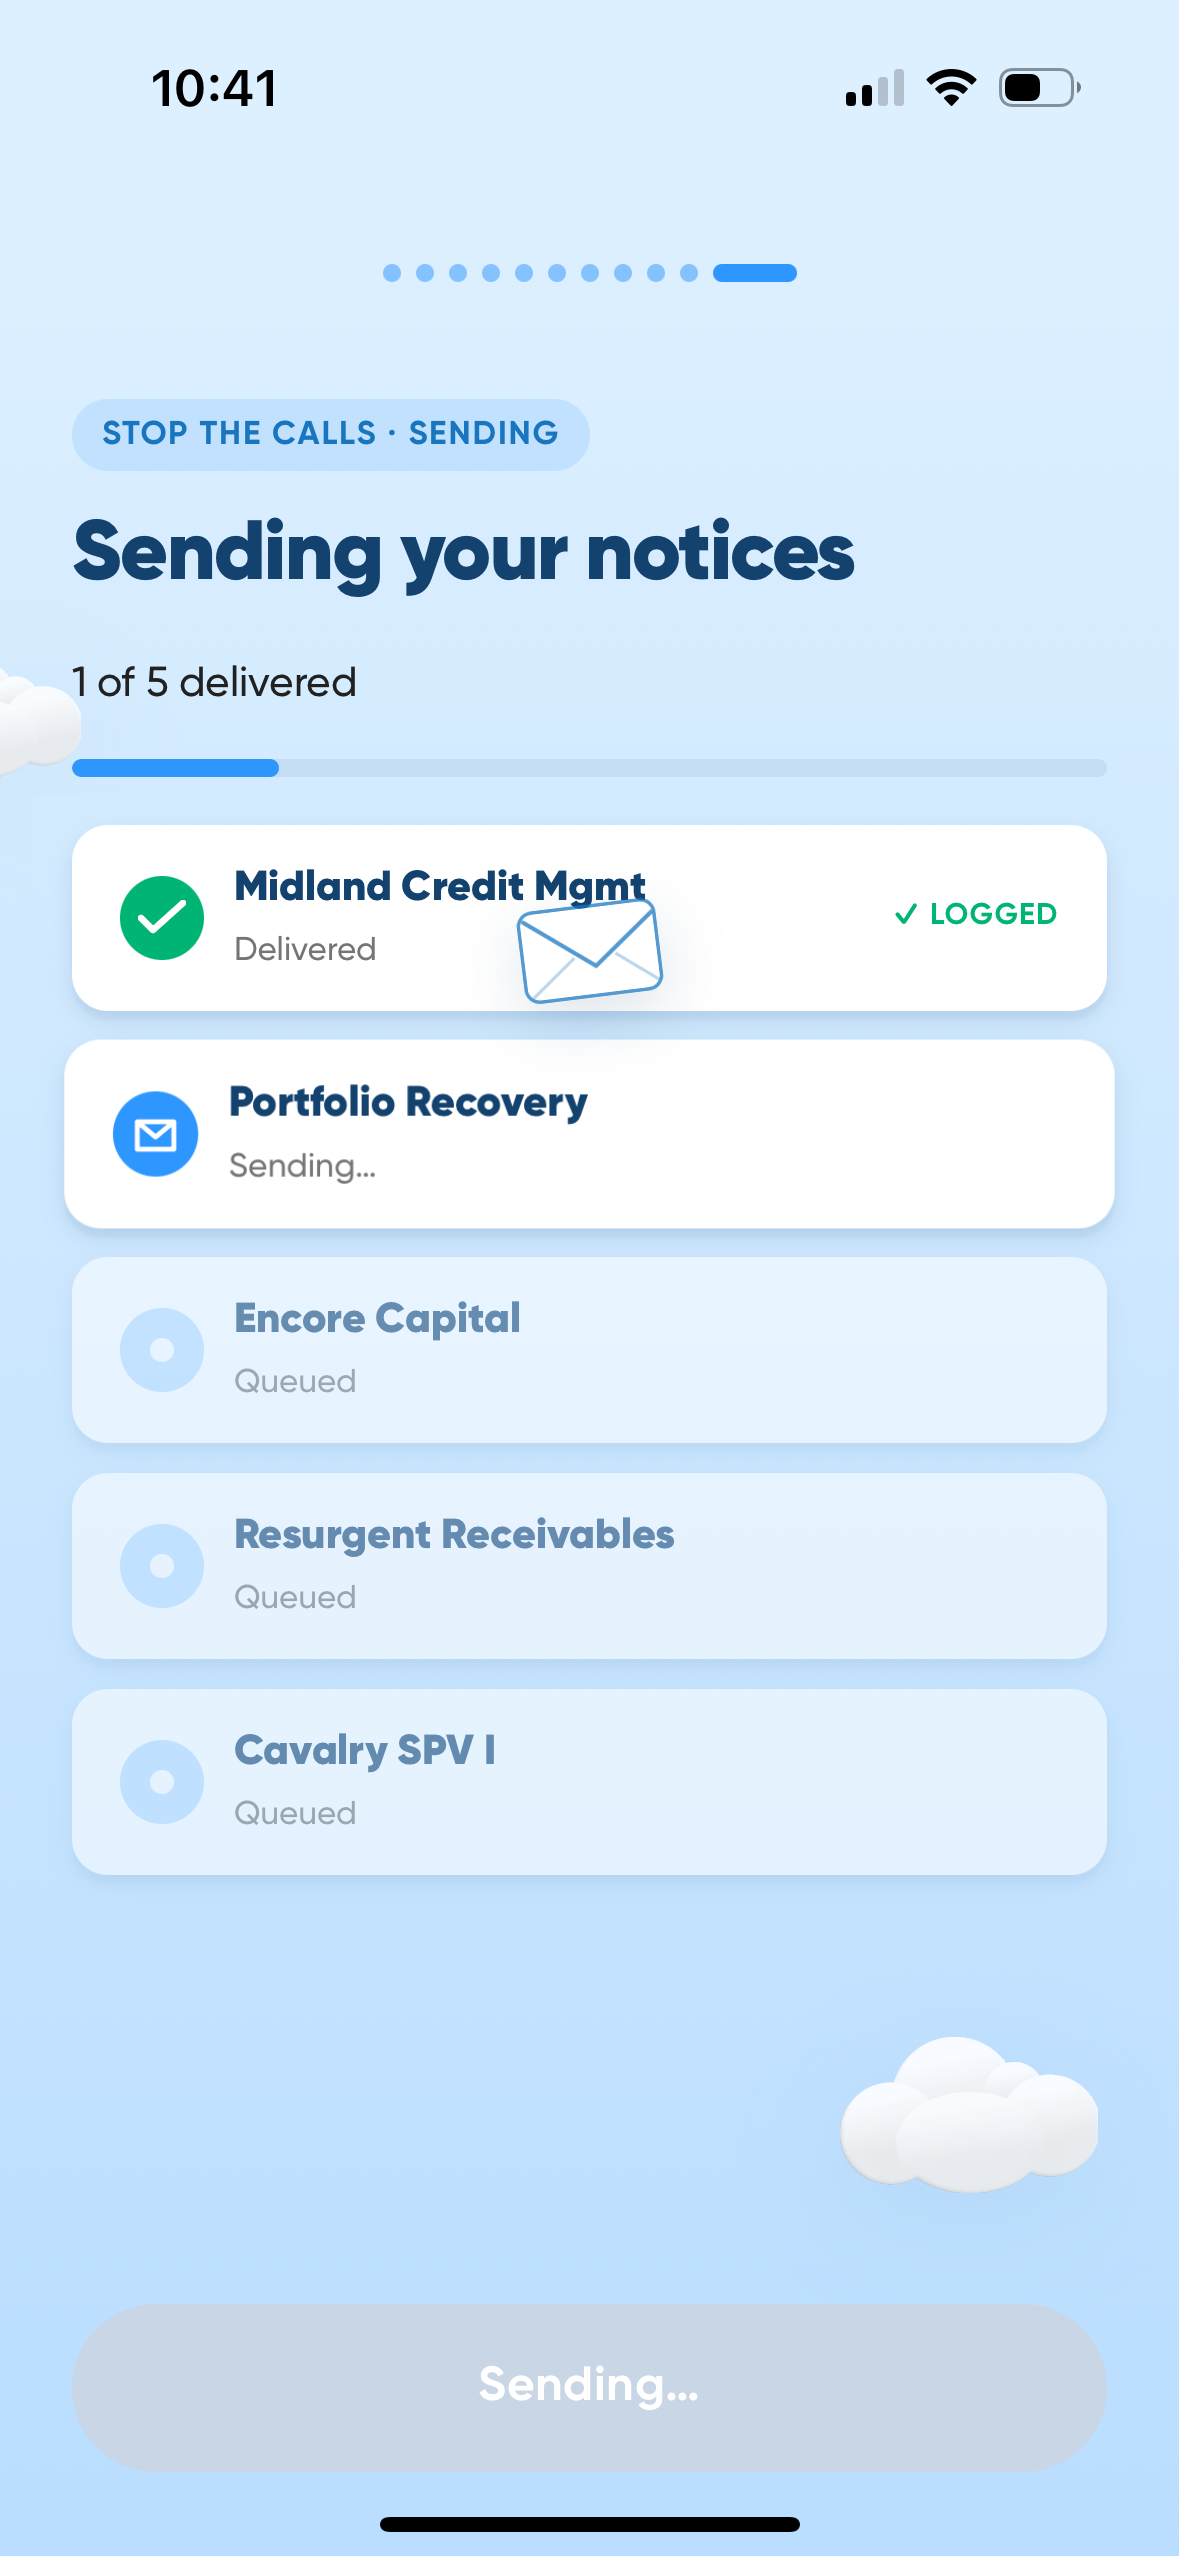
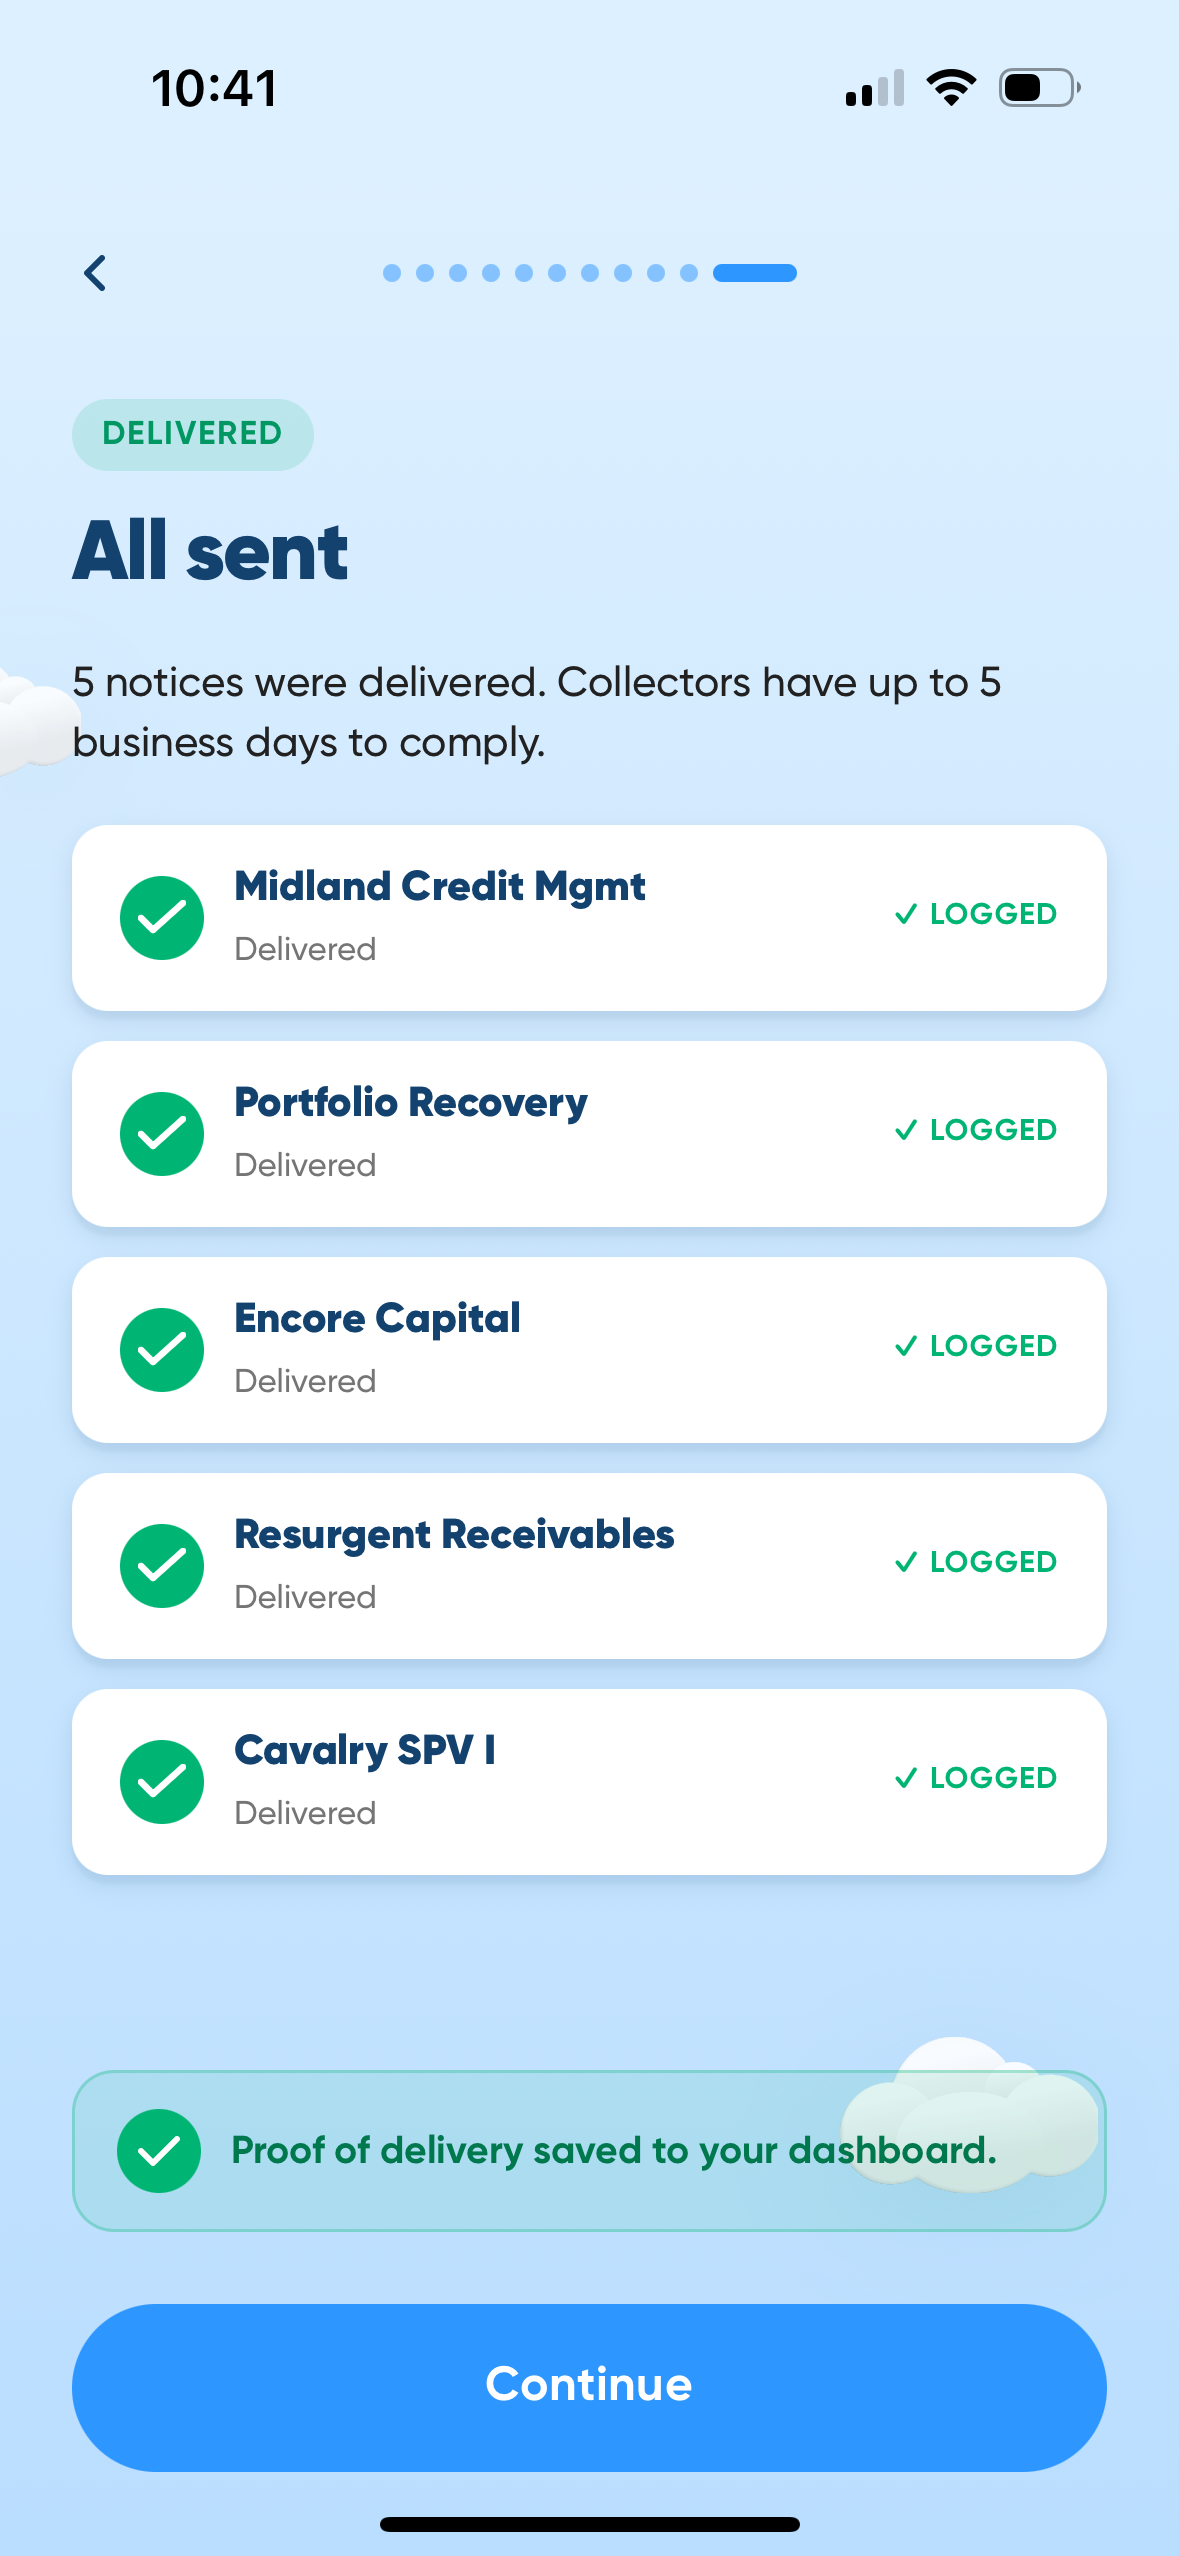
Relief doesn't make decisions for you. You stay in control of what gets submitted and which options you take. No paperwork. No pressure. Just a smarter way to deal with collections.
Creditor eligibility and participation may vary over time. Whether an account qualifies for any Relief tool depends on your creditor's current policies and the information available from your credit report, and can change without notice. A creditor that participates today may not later, and vice versa.
Creditors independently decide whether to accept, reject, or counter any request, and responses may take up to 60 days. Outcomes vary and there is no guarantee of any specific result. You pay your creditor directly.
Legal tools are provided for informational purposes only and do not constitute legal advice or legal representation. Relief is not a law firm; attorney services, where available, are provided by independent attorneys. Deadlines, statutes, and consumer protections vary by state. Relief is not a lender, creditor, or debt collector, and is not affiliated with Nationwide Capital Services.
Key Takeaways
| Topic | What to Know |
|---|---|
| Who Nationwide Capital Services Is | {{Who are they? short}} |
| Why They're Contacting You | You're behind on a debt and they've been hired to collect it, or they bought the account |
| What Happens If You Ignore Them | Continued contact, credit damage, escalation to a law firm, and possible litigation |
| What Rules Apply | The full FDCPA—limits on when they call, how often, what they say, and who else they contact |
| Your Options | Validate the debt, stop the calls in writing, settle for less, or defend a lawsuit |
| How Relief Helps | Cease & desist letters, violation monitoring, reduction requests, and help responding to legal notices |
| What to Do If Sued | Respond within 14–30 days—and check whether the plaintiff is Nationwide Capital Services or a firm acting for them |
Stop guessing at your next move
Relief gives you the tools and the information to act, without the phone calls.
Get started with ReliefMembership from $20/month · self-service platform · not a law firm or debt collector · outcomes vary
Send cease & desist letters in a few taps and log every call as evidence.
⚠️ Think a collector broke the law?
The app flags potential FDCPA violations in what you log.
⚖️ Facing a debt lawsuit?
Get help answering legal notices with a few taps.
💸 Want to reduce a debt?
Request a lower balance when you're ready.