
How to Deal with Gurstel Law Firm(Lawsuits, Settlements, and More)
Relief is the app that helps you save on your debt with smart tools built to do the heavy lifting. With tools like debt reduction requests, you can request lower balances on eligible debts in minutes, and with legal support tools, get help responding to debt notices and review creditor communication for violations. Featured in TechCrunch and backed by leading investors, Relief has already onboarded billions in user's debt. Explore your options and see what's possible.
Who is Gurstel Law Firm?
Gurstel Law Firm is a law firm that specializes in debt collection litigation and judgment enforcement on behalf of creditors, debt buyers, and financial institutions. They are often retained when an account has moved beyond standard collection efforts and requires legal escalation. Gurstel Law Firm may file lawsuits to obtain judgments, which can lead to remedies such as wage garnishment, bank account levies, or property liens where allowed by state law. In addition to litigation, they may attempt to resolve debts before court through settlement negotiations or payment agreements. Their clients include national banks, credit card issuers, commercial lenders, and debt purchasers.Why Is Gurstel Law Firm Contacting Me?
By the time Gurstel Law Firm gets involved, the debt has usually moved past standard collection efforts. A creditor or debt buyer has retained them to escalate the account, which is why you're hearing from a law firm rather than an agency. In some cases you may not even recognize the client they're collecting for, because they weren't the company you originally borrowed from.
If you're hearing from Gurstel Law Firm, it's likely because:
- You fell behind on a credit card or loan
- A creditor or debt buyer has retained them to collect or sue
- They believe you owe the full balance
A letter from a law firm means litigation is on the table. A summons means it has already started. Whether or not the debt is valid, you still have rights. And you have time to act before things escalate.
What happens if I Ignore Gurstel Law Firm?
Ignoring Gurstel Law Firm might feel easier in the short term, but it often leads to bigger consequences down the line. Collection law firms are retained specifically to escalate, so silence tends to move things forward rather than slow them down.
If you ignore collection notices or phone calls:
- They may file suit, which is what a firm at this stage is usually retained to do
- You may continue to receive repeated letters or calls from their office
- The debt may be reported to the credit bureaus, harming your credit score
- Fees or interest may continue to accrue where your contract and state law allow it
If you ignore a lawsuit:
- You risk a default judgment, which means the court automatically rules against you
- That judgment can lead to wage garnishment, frozen bank accounts, or even property liens
- In many states, judgments can remain enforceable for years—and they can be renewed. The longer you wait, the fewer options you may have to settle or negotiate.
The better approach is to understand your rights and take proactive steps to resolve it. Relief can help you do all of that—without the guesswork.
Most people sued over a debt never respond — and lose by default. Relief helps you answer in time.
See howWhat are my options with Gurstel Law Firm?
When you're contacted by Gurstel Law Firm, it can feel overwhelming—but you do have a path forward. Here are three ways you can resolve or defend against the debt:
- Protect yourself in a lawsuit
- Make sure the debt is legitimate
- Settle your debt and get a balance reduction
With a law firm involved, the first one comes first. Deadlines don't wait while you look into the other two.
How do I protect myself if Gurstel Law Firm has filed suit?
Respond in writing, on time. Filing an answer keeps the case alive, forces the other side to prove what they're claiming, and usually leaves the door open to settle. It doesn't mean you're admitting anything. The full breakdown of what to do once you're served is below.
How do I make sure the debt is legitimate?
Before doing anything else, confirm that the debt is accurate. Start by asking:
- Is the debt actually yours?
- Is the amount they claim correct?
- Is the debt still legally collectible (within the statute of limitations)?
- Can they document the chain of ownership, if the account has been sold?
Debt collectors don't always have complete or up-to-date records, and accounts that have passed through several hands often arrive with gaps. If you spot anything incorrect, you can dispute the debt.
You have a 30-day window. After Gurstel Law Firm's first written notice, you generally have 30 days to dispute in writing and request validation. Do that and they generally must pause collection until verification is sent. Put it in writing—a phone call doesn't create the same record. Note that a filed lawsuit runs on its own deadline, and disputing the debt does not pause the court's clock.
What could count as a violation?
A law firm collecting consumer debt is still a debt collector under the Fair Debt Collection Practices Act. Being attorneys doesn't exempt them from the rules—it adds one.
Attorney letters with no attorney involvement
If a letter is presented as coming from an attorney, an attorney has to have been meaningfully involved in reviewing the account. Mass-produced letters on firm letterhead that no lawyer ever looked at may misrepresent attorney involvement.
Calling before 8 a.m. or after 9 p.m.
Calls must happen during allowed hours—in your local time zone, not theirs. A 6:45 a.m. or 9:15 p.m. call may be worth documenting.
Calling more than 7 times in 7 days
Under CFPB Regulation F, collectors generally can't call more than seven times within seven days about the same debt—and after a conversation, they generally must wait seven days before calling again.
Contacting you after a cease & desist letter
After receiving a written cease & desist, Gurstel Law Firm generally must stop—they can confirm receipt or give notice of a specific action, and that's about it. Filing suit is one of the actions they can still notify you about, so a cease & desist doesn't stop litigation.
Contacting you directly once you have a lawyer
If they know you're represented by an attorney on this debt, communication generally has to go through your lawyer, not to you.
Calling your workplace after being told not to
Once they're told an employer doesn't allow those calls, they must stop calling there. No proof required—telling them is enough.
Discussing the debt with other people
Debt is private. They generally can't discuss it with family, friends, coworkers, neighbors, or employers. They may contact someone once—only to confirm location, never to mention the debt.
Threatening arrest or jail
"You'll be arrested if you don't pay."
Nobody goes to jail for unpaid consumer debt. It's a civil matter, not a criminal one.
Threatening suits or garnishment that isn't coming
"Your paycheck will be garnished tomorrow."
Wage garnishment requires a lawsuit, a judgment, and a court order—it can't happen instantly. They can't claim legal action was filed when it wasn't, or threaten a suit they don't intend to bring.
Suing on a debt past the statute of limitations
Every state limits how long a creditor has to sue. Filing or threatening suit on a time-barred debt may itself violate the FDCPA—and the deadline is measured from your original delinquency, not from when the account was last sold.
Inflating the balance
No fake fees, no unauthorized interest, no collecting debt that isn't real or was already paid. Court costs and attorney's fees can only be added if your contract or state law allows it.
Abusive or threatening language
No swearing, no threats of harm, no humiliation, no intimidation. Behavior designed to degrade or frighten may violate the FDCPA on its own.
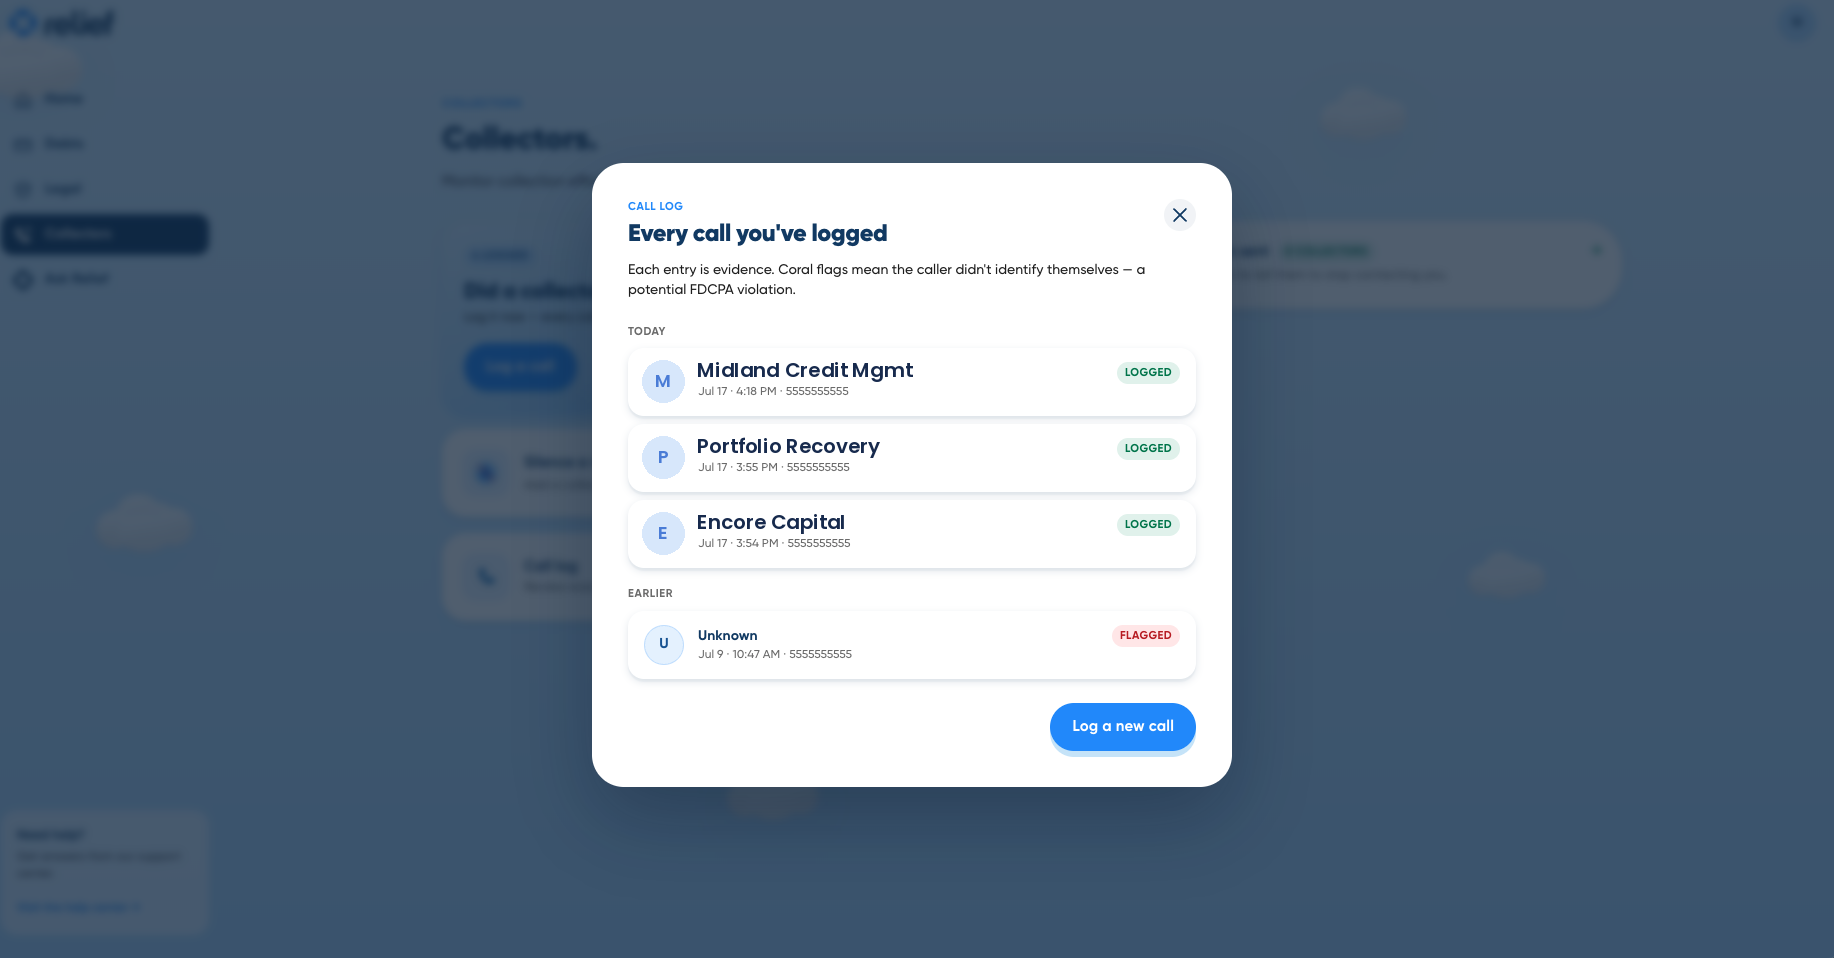
Keep the receipts Relief members log calls, letters, and voicemails in seconds — and the app turns them into a timestamped case file.
See howRelief lets you log every call and letter, flags activity that may deserve a closer look, and keeps it all as a timestamped record. Federal law allows up to $1,000 in statutory damages per lawsuit, and in some cases actual damages and attorney's fees. Outcomes vary, depend on the evidence and the specific conduct, and are never guaranteed.
How do I settle a debt with Gurstel Law Firm?
If the debt is valid and you're in a position to resolve it, you may be able to pay less than the full amount owed. Relief's debt reduction requests are designed to help you take control of the situation—without the endless back-and-forth or pressure tactics of traditional settlement approaches.
With a reduction request, you can:
- Secure a lower payoff amount
- Avoid the stress of phone calls and negotiations
- Submit your request automatically within minutes, right through the Relief app
We've seen users save between 35% and 60% off their original balance, sometimes even more. But it all depends on your creditor and your circumstances. The process is fully automated and self-guided, meaning you stay in control at every step. We work directly with your creditor to present a strong, data-backed offer that increases your chances of approval.
Why does this work?
Because a firm at this stage is generally paid on what it recovers, and litigation costs money. A well-structured offer is far more appealing than a contested case that might be dismissed, or a judgment against someone with nothing to collect.
Ultimately, getting something is better than getting nothing. Settlement offers give both parties a clean resolution: you pay less, and they close the file and move on.
Settling your debt not only saves you money, but also helps close the chapter so you can start rebuilding your credit and move forward without the constant stress of collections.
Settling can happen after a suit is filed. Most collection cases resolve before trial. Answering the complaint and negotiating are not mutually exclusive—in practice, filing an answer often improves your position.
What if Gurstel Law Firm isn't eligible for automated requests?
Eligibility varies, and not every creditor supports requests submitted through the app. If Gurstel Law Firm isn't currently eligible, Relief can still help you prepare:
- Estimated benchmark data, where available
- A conversation blueprint with suggested talking points
- Guidance on what to gather before you reach out
- Recommended questions to ask
You stay in control and decide whether to contact Gurstel Law Firm directly.
Relief makes it easy to request a lower balance. Your creditor decides from there.
Get ReliefWill Gurstel Law Firm settle for less?
Collection firms will often settle for less than the full balance you owe. Many people are able to resolve their accounts for less, especially if the debt is older or you're able to make a lump-sum payment. That said, Gurstel Law Firm is under no obligation to make an offer, and the outcome depends specifically on your account and their client's instructions.
Gurstel Law Firm is suing me. What should I do?
If you have a lawsuit against you, the worst thing you can do is ignore it. Once you're officially served with court documents—a summons and complaint—you're on the clock. Most courts give you just 14–30 days to respond, depending on your state.
Missing the deadline is how default judgments happen
If you ignore the summons, the judge may issue a default judgment, giving the plaintiff the legal right to garnish your wages, freeze your bank accounts, and add court fees and legal costs to your debt.
Filing a response is critical. It keeps the case alive, makes the other side prove what they're claiming, and usually leaves the door open to settle.
A summons notifies you of the lawsuit and includes key details like:
- The name and location of the court
- The names of both parties
- Your case number
- Deadlines for your response
A complaint outlines what the creditor is claiming, often in numbered paragraphs. Together, these documents kick off the legal process, and the clock starts ticking.
Check the plaintiff's name carefully. Gurstel Law Firm is the firm handling the case, but the party suing you may be a creditor or a debt buyer they represent.
And with Relief's legal support tools, you don't have to do it on your own.
Here's how Relief helps you respond:
- AI-assisted review of the summons, complaint, and any notices you've received
- Response drafting support and instructions for filing your answer
- A review of the account and the contact history for potential violations
- Access to independent attorneys at preferred pricing, with a free consultation scheduled in the app
This not only protects you from default judgment, but also gives you the option to still settle the debt—often for less than the full amount.
How to Get Help
When a law firm is involved, the deadline matters more than anything else. Your Relief membership includes tools for understanding the paperwork, responding to it, and resolving the balance.
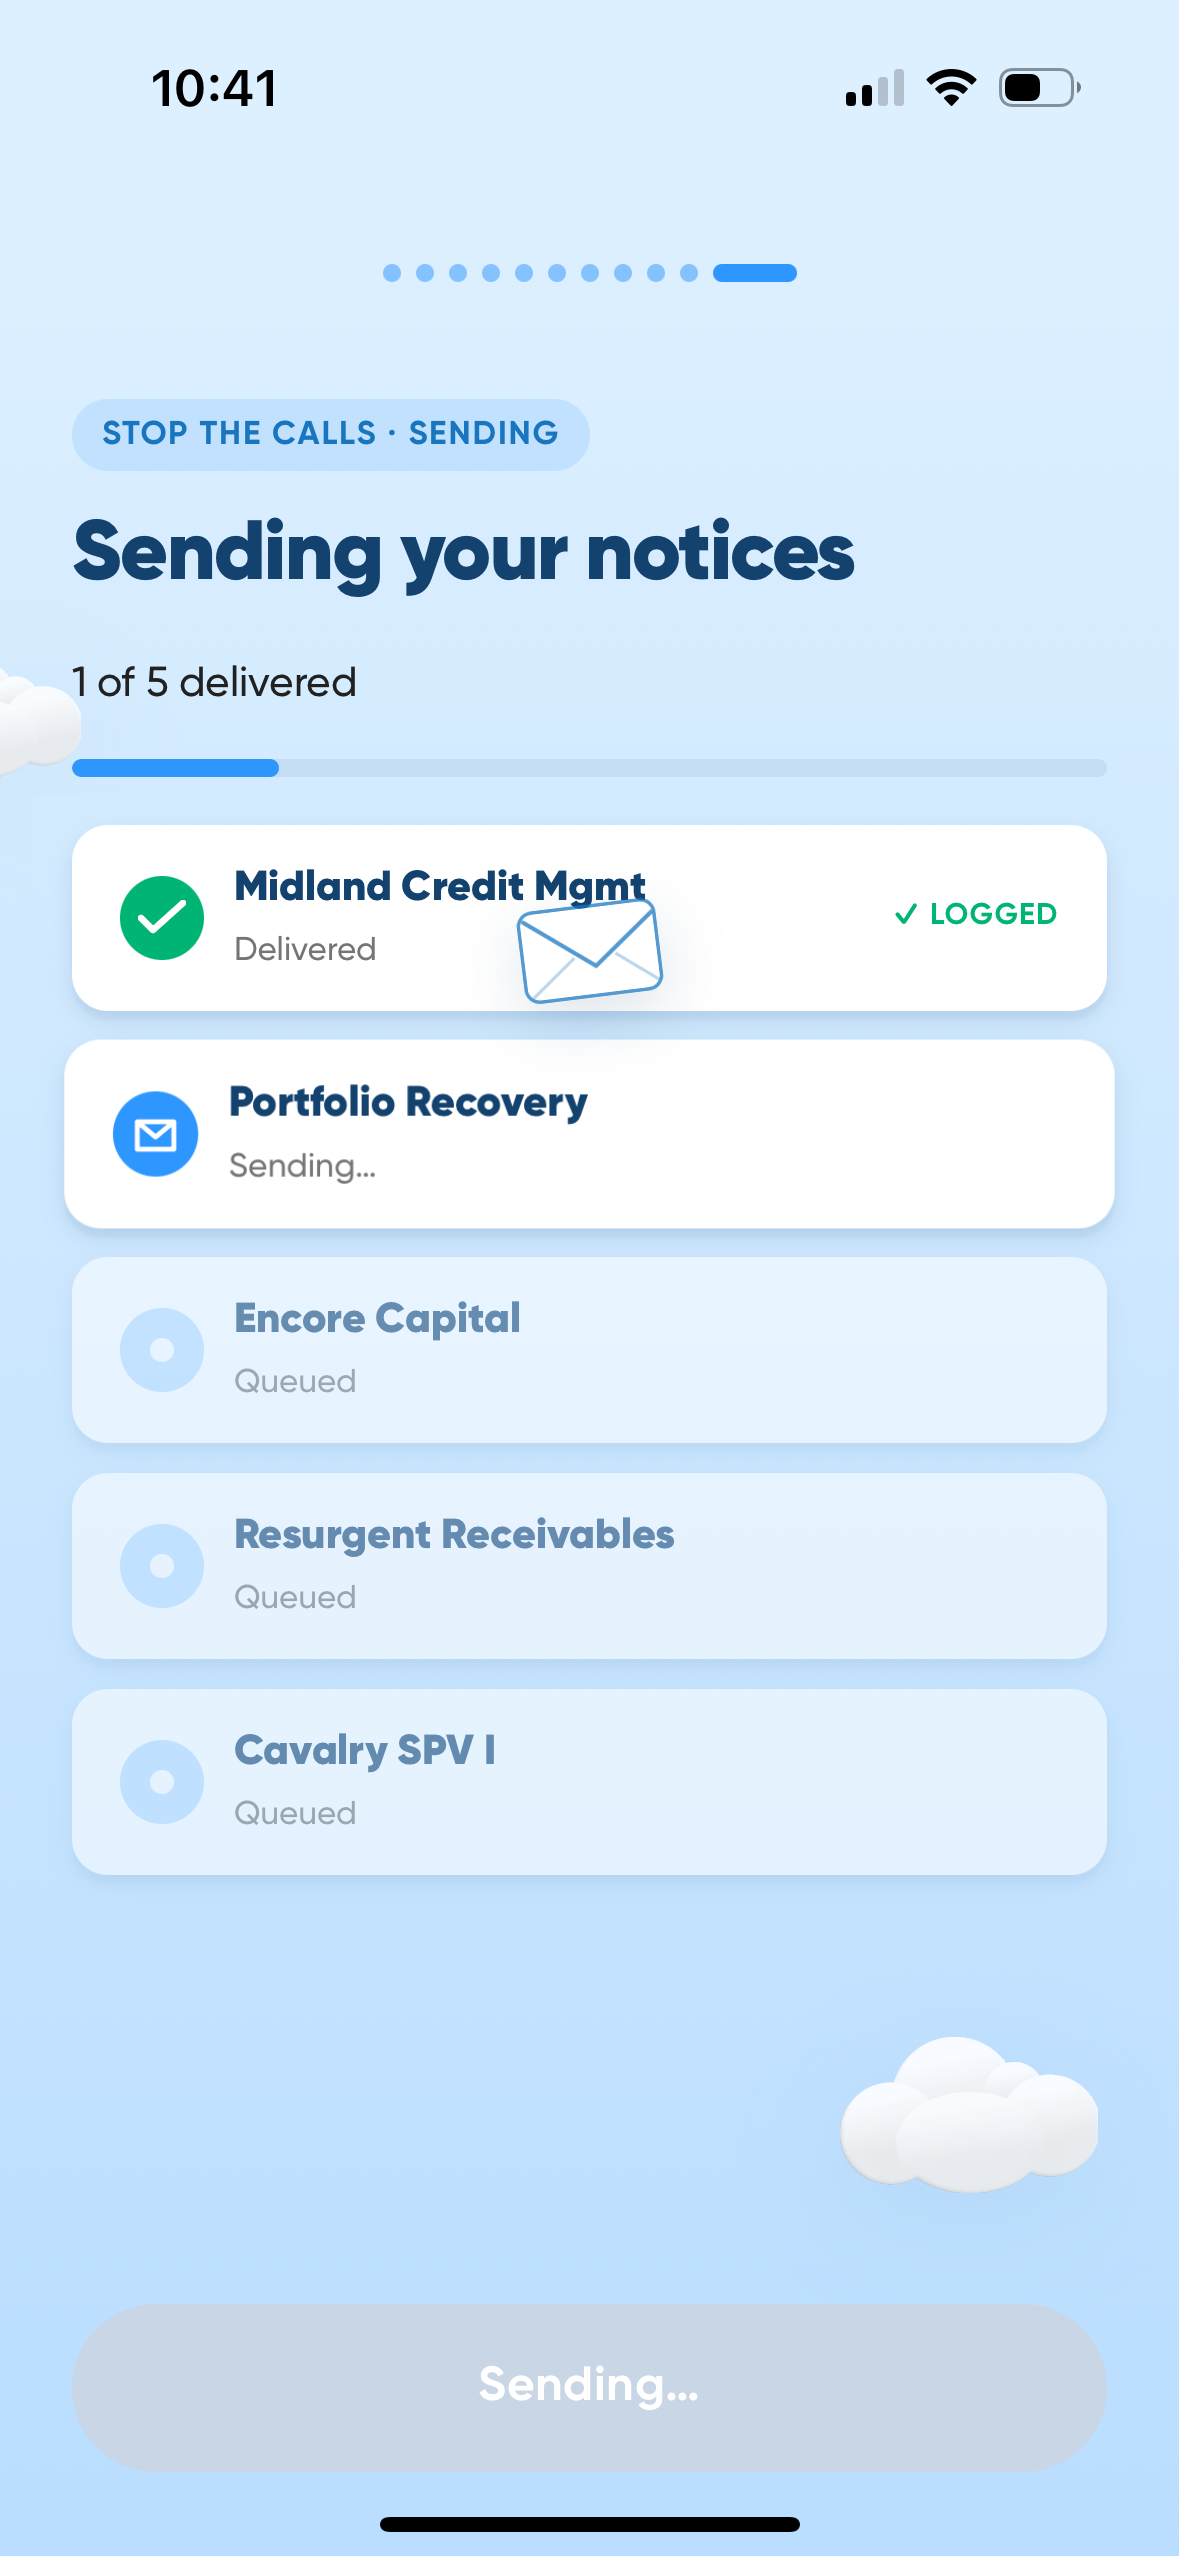
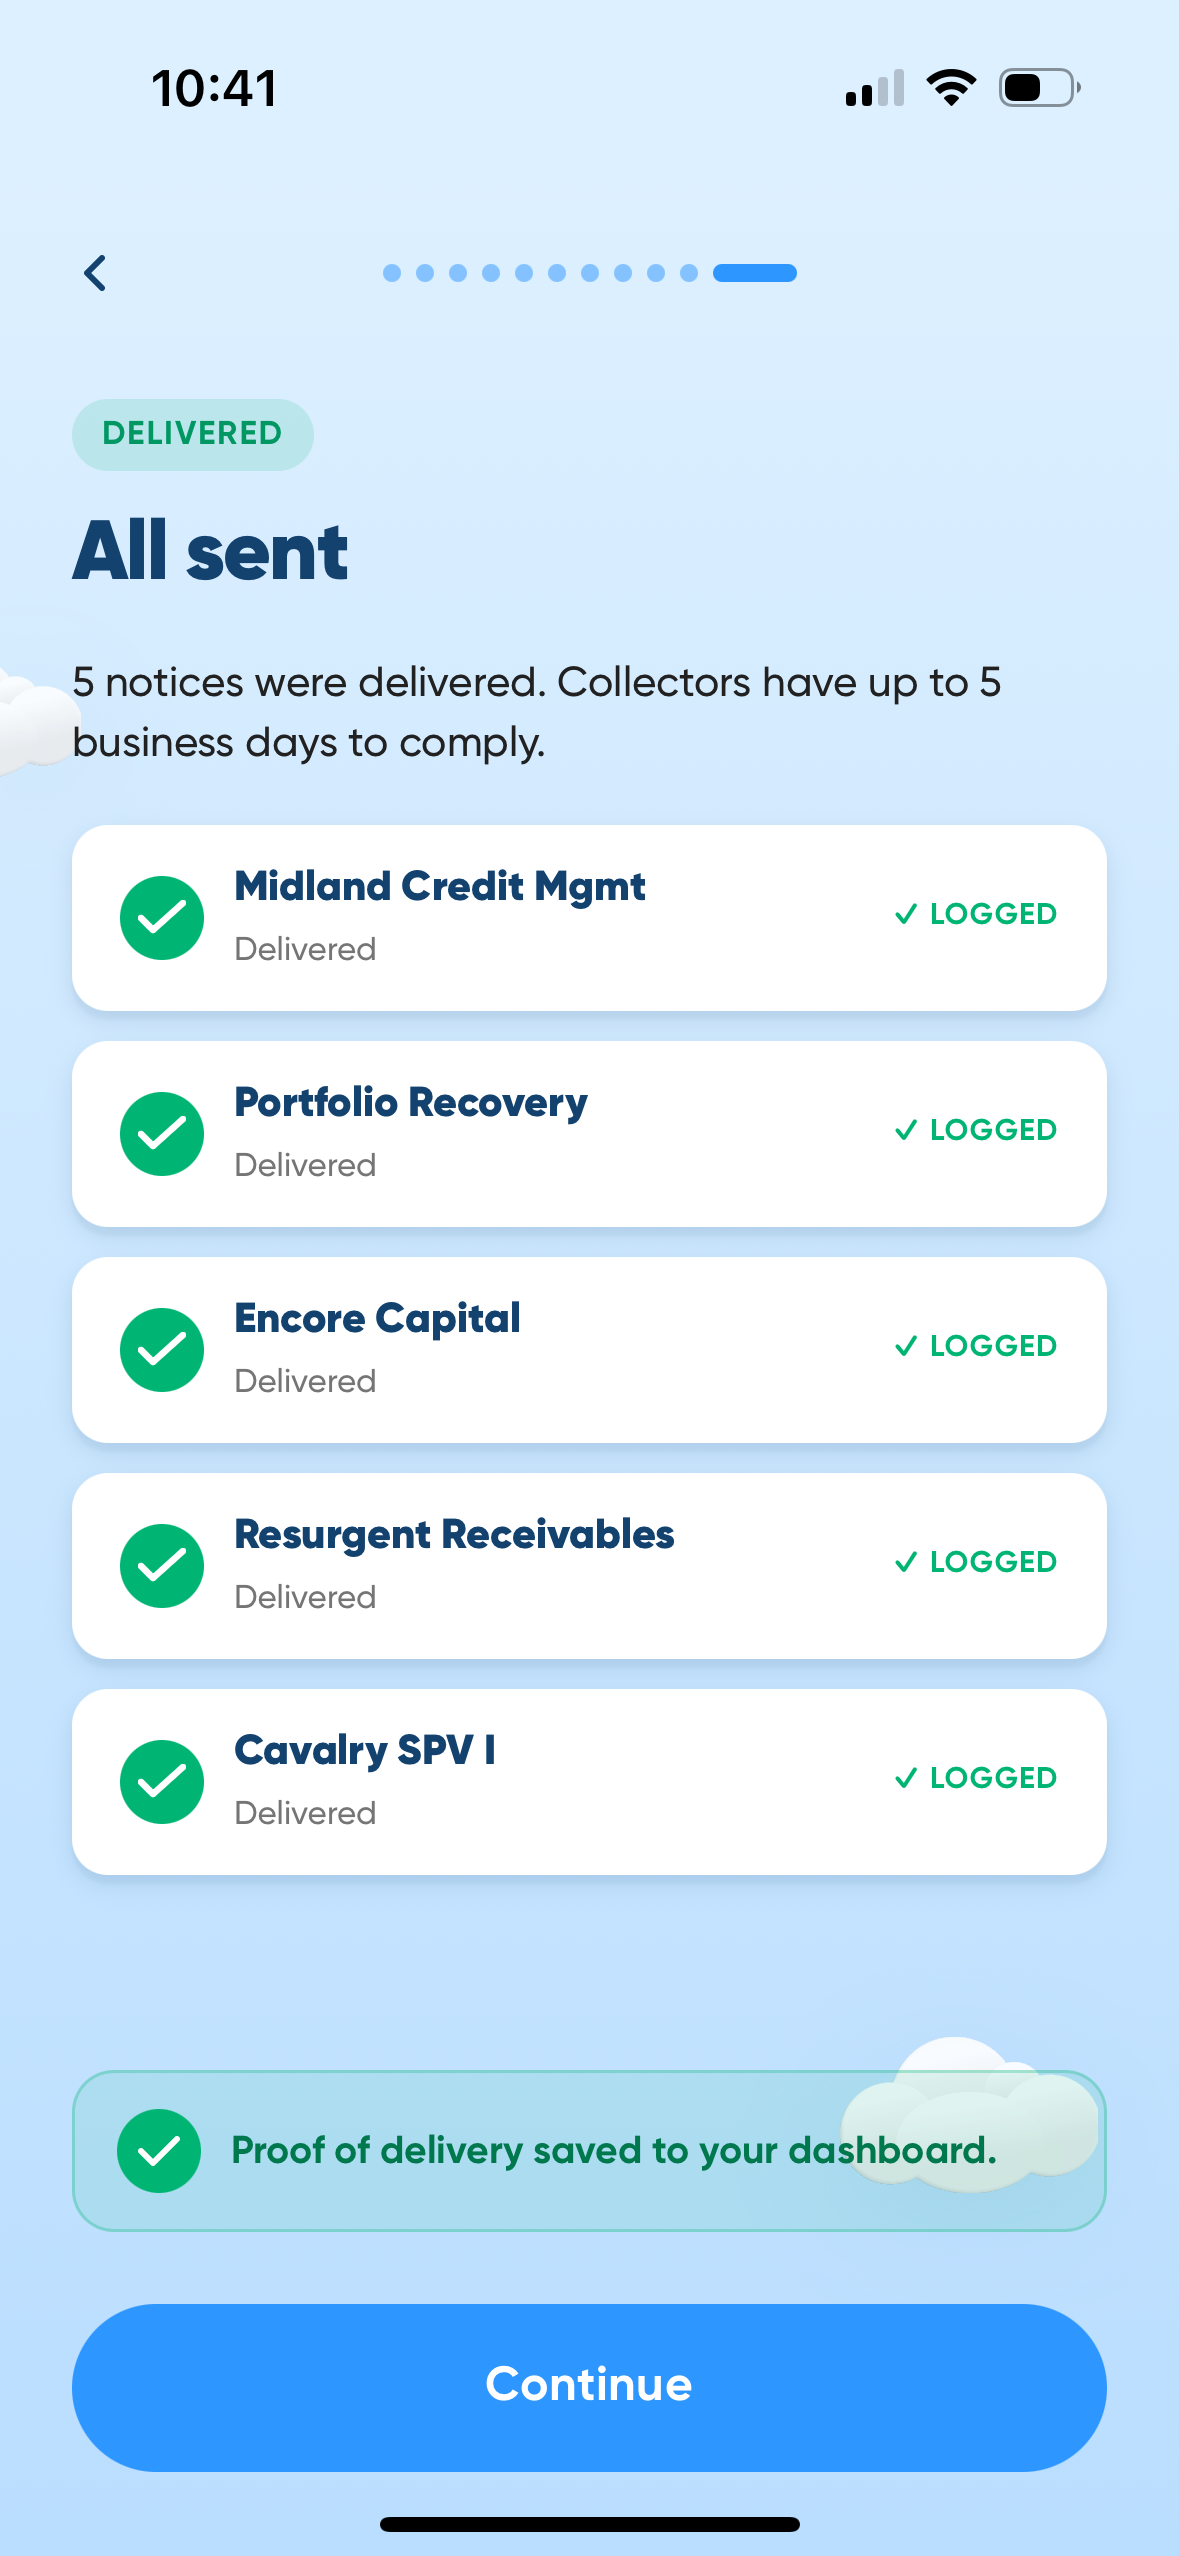
Relief doesn't make decisions for you. You stay in control of what gets submitted and which options you take. No paperwork. No pressure. Just a smarter way to deal with collections.
Creditor eligibility and participation may vary over time. Whether an account qualifies for any Relief tool depends on your creditor's current policies and the information available from your credit report, and can change without notice. A creditor that participates today may not later, and vice versa.
Creditors independently decide whether to accept, reject, or counter any request, and responses may take up to 60 days. Outcomes vary and there is no guarantee of any specific result. You pay your creditor directly.
Legal tools are provided for informational purposes only and do not constitute legal advice or legal representation. Relief is not a law firm; attorney services, where available, are provided by independent attorneys. Deadlines, statutes, and consumer protections vary by state. Relief is not a lender, creditor, or debt collector, and is not affiliated with Gurstel Law Firm.
Key Takeaways
| Topic | What to Know |
|---|---|
| Who Gurstel Law Firm Is | Creditors’ rights law firm that files collection lawsuits for lenders/debt buyers. |
| Why They're Contacting You | A creditor or debt buyer retained them to collect or sue on a past-due account |
| What Happens If You Ignore Them | A filed suit, a default judgment, wage garnishment, and long-term credit damage |
| What Rules Apply | The FDCPA still applies to law firms collecting consumer debt, including limits on contact and on misrepresenting attorney involvement |
| Your Options | Answer the suit, validate the debt, or settle for less—often all three |
| How Relief Helps | Document review, response drafting, violation monitoring, reduction requests, and discounted attorney access |
| What to Do If Sued | Respond within 14–30 days—Relief can help you review the paperwork and file your answer |
Stop guessing at your next move
Relief gives you the tools and the information to act, without the phone calls.
Get started with ReliefMembership from $20/month · self-service platform · not a law firm or debt collector · outcomes vary
Send cease & desist letters in a few taps and log every call as evidence.
⚠️ Think a collector broke the law?
The app flags potential FDCPA violations in what you log.
⚖️ Facing a debt lawsuit?
Get help answering legal notices with a few taps.
💸 Want to reduce a debt?
Request a lower balance when you're ready.